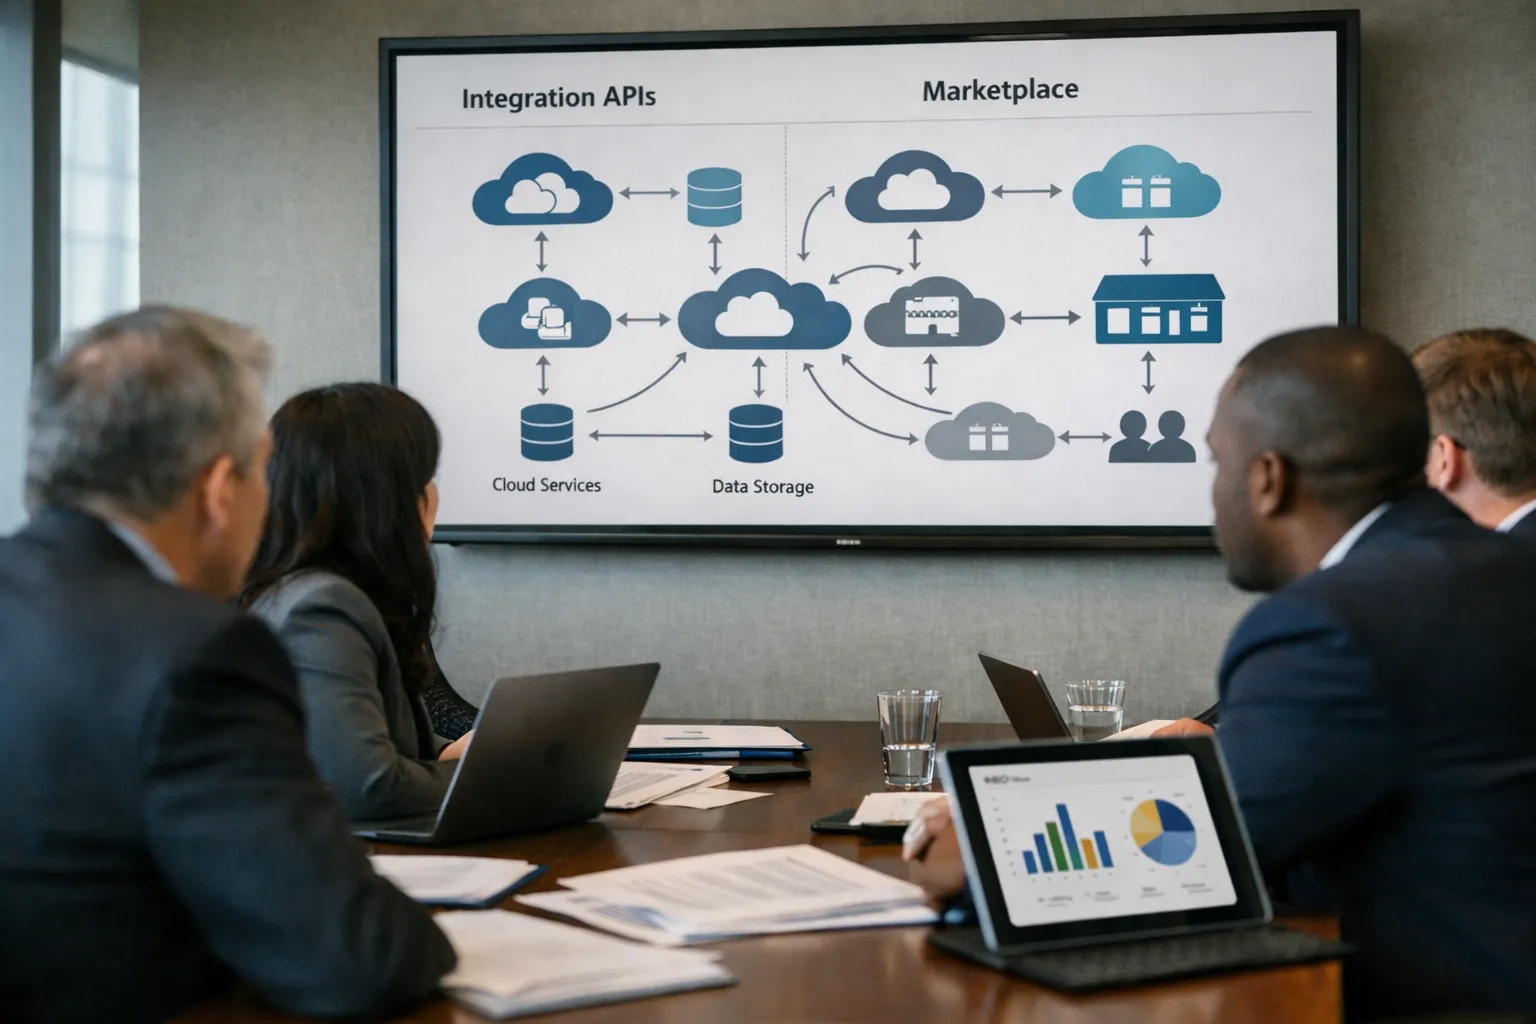
Brussels — The European Union's Digital Markets Act (DMA) is moving from law to practice, and enterprise software buyers are beginning to see concrete impacts on vendor roadmaps, integration approaches and implementation timelines. Companies that sell or buy large-scale cloud platforms and adjacent enterprise solutions are recalibrating procurement requirements to factor in new openness, interoperability and measurable ROI.
From principle to procurement: what’s changing
Passed to curb platform gatekeeper practices, the DMA requires designated "gatekeepers" to provide interoperable access and non-discriminatory interfaces for third parties. For enterprise buyers, that legal push translates into tangible changes: vendors are being asked to document and expose integration APIs, enable data portability between competing services, and support multi-vendor workflows without onerous lock-in.
For CIOs and procurement teams, the practical effect is twofold. First, requests for proposals now routinely include detailed requirements for integration endpoints, lifecycle support for connectors, and SLAs that account for cross-provider orchestration. Second, total cost-of-ownership models increasingly factor in expected implementation effort for integrating newly exposed APIs and verifying scalability under production workloads.
Vendors adapt their roadmaps
- Opening previously proprietary integration points. Major cloud and collaboration vendors are revising their product roadmaps to publish documented APIs and SDKs that ease third-party integration.
- Publishing compatibility and portability guides. Expect more formal vendor artifacts resembling model cards or SBOMs, but focused on integration contracts and migration paths for enterprise solutions.
- Building marketplaces and partner programs designed around interoperable modules. Vendors are moving from closed app ecosystems to curated marketplaces where third-party modules can plug into vendor platforms without bespoke engineering.
Why this matters for scalability and implementation
Enterprise software buyers evaluate scalability not only in raw throughput but also in how well a solution composes with existing components at scale. Open integration APIs reduce brittle, one-off connectors and enable standardized orchestration layers. That makes it easier to scale horizontally across geographies and business units because integration becomes repeatable rather than bespoke.
However, the transition is not frictionless. Implementation timelines can lengthen in the short term as enterprises rework existing integrations to rely on standard APIs rather than custom adapters. Integration testing, regression analysis and performance validation across heterogeneous stacks become table-stakes activities for large deployments.
Impact on ROI calculations
Procurement teams must adjust ROI assumptions. There are several implications:
- Upfront costs may rise. Migrating away from bespoke connectors can require one-time engineering investments to refactor or replace legacy glue code.
- Operational cost savings emerge over time. Once integrations use standardized interfaces, maintenance burdens fall and vendor upgrades become less disruptive, improving long-term TCO.
- Faster vendor substitution reduces lock-in risk. The ability to switch providers more easily can strengthen negotiating leverage and reduce renewal price inflation, a material ROI benefit for multi-year contracts.
What buyers should ask vendors today
Enterprise technology leaders should make DMA-driven openness a concrete part of vendor evaluation. At minimum, request:
- Published API specifications, versioning and deprecation policies for integration endpoints.
- Reference architectures and scalability tests demonstrating how integrations perform at expected concurrency and throughput levels.
- Clear data portability mechanisms (export formats, schemas and tools) and documented migration playbooks.
- Commercial terms that address multi-vendor deployments, including support responsibilities when components cross vendor boundaries.
- Case studies quantifying implementation effort and realized ROI from customers that adopted the vendor’s open-integration approach.
Risks and open questions
Despite broad benefits, buyers and vendors face unresolved issues. Interoperability can be limited by implementation choices—APIs may be open but vary in semantic behavior, requiring translation layers. Security and compliance are another concern: exposing deeper integration hooks increases the attack surface and raises questions around joint responsibility for incident response.
There is also a timing risk. Vendors may prioritize market-facing APIs first (marketplaces, billing, identity) and defer deeper platform internals (telemetry, control-plane APIs). Procurement teams need to assess which integration layers matter for their use cases and insist on those being available or contractually committed in the roadmap.
Early wins and real-world signals
Some enterprises that have piloted the new integration-first approach report faster onboarding for partner solutions and simpler cross-cloud dataflows. Portability has already reduced the friction of proofs-of-concept that previously stalled due to proprietary hooks. For large organizations with heterogeneous stacks, those wins compound: reusable connectors and standardized orchestration reduce per-project implementation cost, and that accelerates ROI realization across lines of business.
Analysts advise treating DMA-driven openness as a strategic enabler rather than a checkbox compliance item. When vendors expose integration contracts and support composable deployment patterns, enterprises can move from multi-year monolithic rollouts toward more iterative, measurable implementations.
Bottom line
The DMA is reshaping how enterprise software is bought and built: openness and standardized integration are becoming contractual expectations that affect scalability, implementation effort and long-term ROI. For procurement teams, the immediate task is operationalizing these expectations into RFPs, SLAs and vendor roadmaps. For vendors, the work is technical and commercial—releasing APIs, documenting portability, and rethinking partner ecosystems to win in a market that increasingly values composability over lock-in.